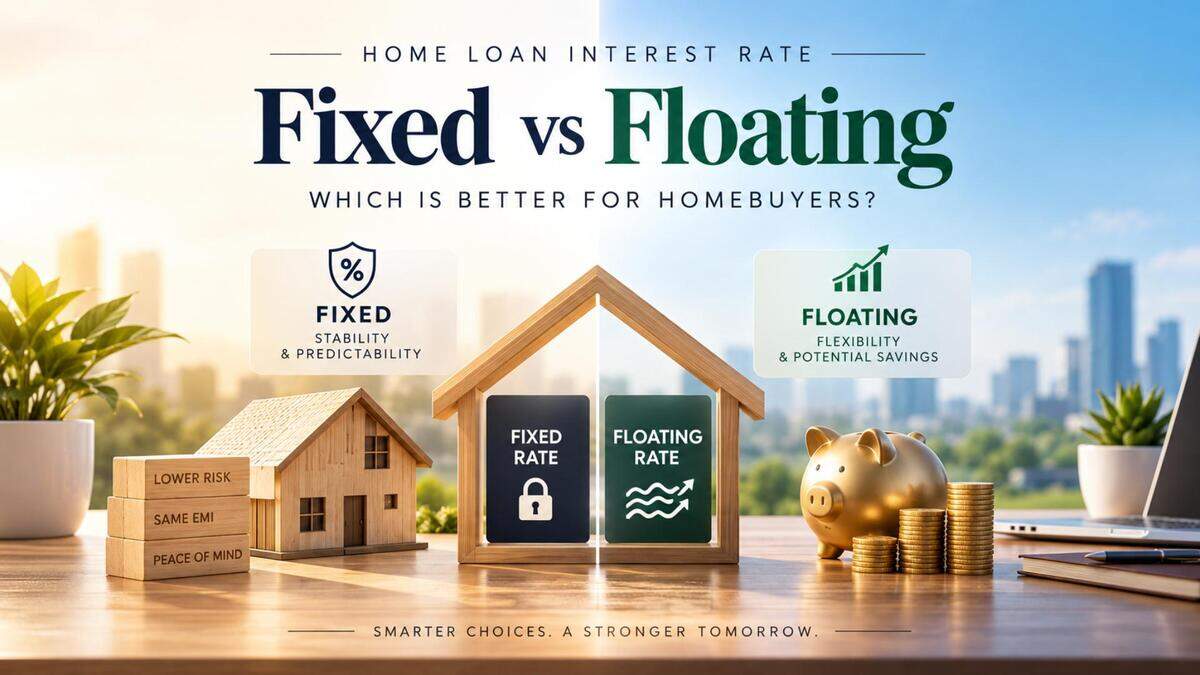
Home Loan Interest Rate: Fixed vs Floating - Which is Better for Homebuyers
Understand the pros and cons of fixed vs floating home loan interest rates and how to choose the best option for your budget and risk profile.
This blog explains how home loan interest rates work, breaks down fixed and floating-rate home loans, compares them head-to-head, and helps you decide which suits your budget, risk appetite, and timeline.
Understanding Home Loan Interest Rates
A home loan interest rate is the percentage a bank charges you to borrow money for buying a house. It determines your monthly EMI, total outflow, and tenure.There are two main types of home loan interest rates:
- Fixed interest rate: The rate stays the same for the entire loan tenure (or a fixed period).
- Floating (variable) interest rate: The rate can change with market conditions, usually linked to repo rate, MCLR, or EMR.
Fixed Interest Rate
In a fixed interest home loan, the rate remains constant for the entire tenure (or a pre‑decided fixed period, typically 5-10 years). Your EMI stays the same, even if market rates go up or down.This suits buyers who want stability and predictability in their monthly outflow.
Benefits of Fixed Interest Rate
- EMI predictability: You know your EMI will not change, which helps with budgeting and planning.
- Protection from rate hikes: If market rates increase, your fixed rate remains the same, so you’re not impacted.
- Suitable for long‑term planning: Ideal for long‑term homeowners, salaried individuals, or families who want stable monthly expenses.
Drawbacks of Fixed Interest Rate
- Higher initial interest rate: Fixed rates are usually 1-1.5% higher than floating rates, so you pay more upfront.
- Limited flexibility: You cannot switch to a lower rate if market conditions improve.
- Long‑term risk: If market rates fall, you miss out on lower EMIs and reduced total interest.
Floating Interest Rate
In a floating (variable) interest rate home loan, the rate fluctuates with market conditions, typically linked to repo rate, MCLR, or EMR. Your EMI can increase or decrease over time.This suits buyers who are comfortable with rate volatility and expect that market rates may fall in the future.Choosing between fixed and floating interest rates depends on your financial situation, risk appetite, and market expectations. With interest rates expected to fluctuate, here are the key points:If you’re unsure, consult a financial advisor or use home loan calculators to simulate EMIs under different scenarios.If you’re planning to buy a luxury or Delhi‑NCR, TOI Homes makes the home loan process easier and more transparent. Discover how can help you buy your dream home with a smart home loan.Frequently asked QuestionsFAQs
- Fixed interest rates are best for long-term, careful borrowers who want predictable EMIs. - Floating interest rate are ideal for short-term or flexible-budget borrowers who can handle EMI fluctuations.
Disclaimer: The information presented by TOI Homes, part of The Times of India Group, is for general informational purposes only and does not constitute financial, legal, or investment advice. All data and insights are based on sources believed to be reliable but are not guaranteed for accuracy or completeness and are subject to change due to market conditions. The developer and associated entities are not liable for decisions made based on this information. Real estate investments involve risks, and buyers are advised to conduct independent due diligence and consult certified advisors before investing. TOI Homes does not endorse or promote any specific property or developer unless explicitly stated.